Starting a new job is usually a positive step, but the first few months can create financial uncertainty. You may need to pay relocation expenses, replace essential equipment, manage medical costs or cover household bills before receiving several full salary payments.
If you are still serving your employment probation, you may wonder whether a lender will consider your application.
The short answer is yes, you may apply for a personal loan during probation in Singapore. However, approval is not guaranteed. The lender will assess your current employment, verified income, existing commitments and ability to manage the proposed repayments.
This guide explains which documents to prepare, how a short employment history may affect the assessment and what to consider before accepting a loan.
Quick Answer
An employee on probation may submit a personal loan application in Singapore. There is no general rule stating that every applicant must first complete probation.
However, a lender may request additional evidence because the employment relationship is relatively new. Useful documents can include an employment contract, recent payslips, bank statements, CPF contribution records and previous employment records.
Every application remains subject to verification, affordability assessment and approval.
What Does Employment Probation Mean?
An employment probation period is an initial period during which the employer assesses whether a new employee is suitable for the role.
The length depends on the employment contract. A probation period commonly lasts between three and six months, although the actual duration can be shorter or longer.
During this period, the employee may already receive:
- A regular monthly salary
- Employer CPF contributions
- Allowances
- Overtime payments
- Sales commissions
- Other contractual benefits
Being on probation does not necessarily mean the employee has no income. The main concern for a lender is whether the income can be verified and whether it is sufficiently stable to support the requested repayments.
Can You Apply for a Personal Loan While on Probation?
Yes. An employee may apply while serving probation, subject to the lender’s assessment.
A licensed moneylender may consider:
- Your current monthly salary
- Whether you have received a full salary payment
- Your employment commencement date
- The length of your probation
- Your previous employment history
- Existing loans and repayments
- Monthly living expenses
- Your repayment record
- The amount requested
- Your proposed loan tenure
A new job alone does not guarantee approval or rejection. The lender should review the applicant’s overall financial circumstances.
You can check the general personal loan options available from EZ Pte Ltd before deciding whether to apply.
Why Can Probation Affect a Loan Application?
A probationary employee has a shorter income history with the current employer. This can make it more difficult to determine whether the salary will continue throughout the proposed repayment period.
For example, the lender may need to establish:
- Whether the employment is permanent or temporary
- Whether the salary stated in the contract has been received
- Whether the applicant has completed at least one full pay cycle
- Whether the probation period has been extended
- Whether the role depends heavily on overtime or commission
- Whether there was a long gap before the new employment began
- Whether the requested instalment remains affordable using basic salary
Probation is only one assessment factor. An applicant with a clear employment contract, regular salary credit and manageable expenses may present a different risk profile from someone whose employment and income cannot yet be verified.
What Documents Should You Prepare?
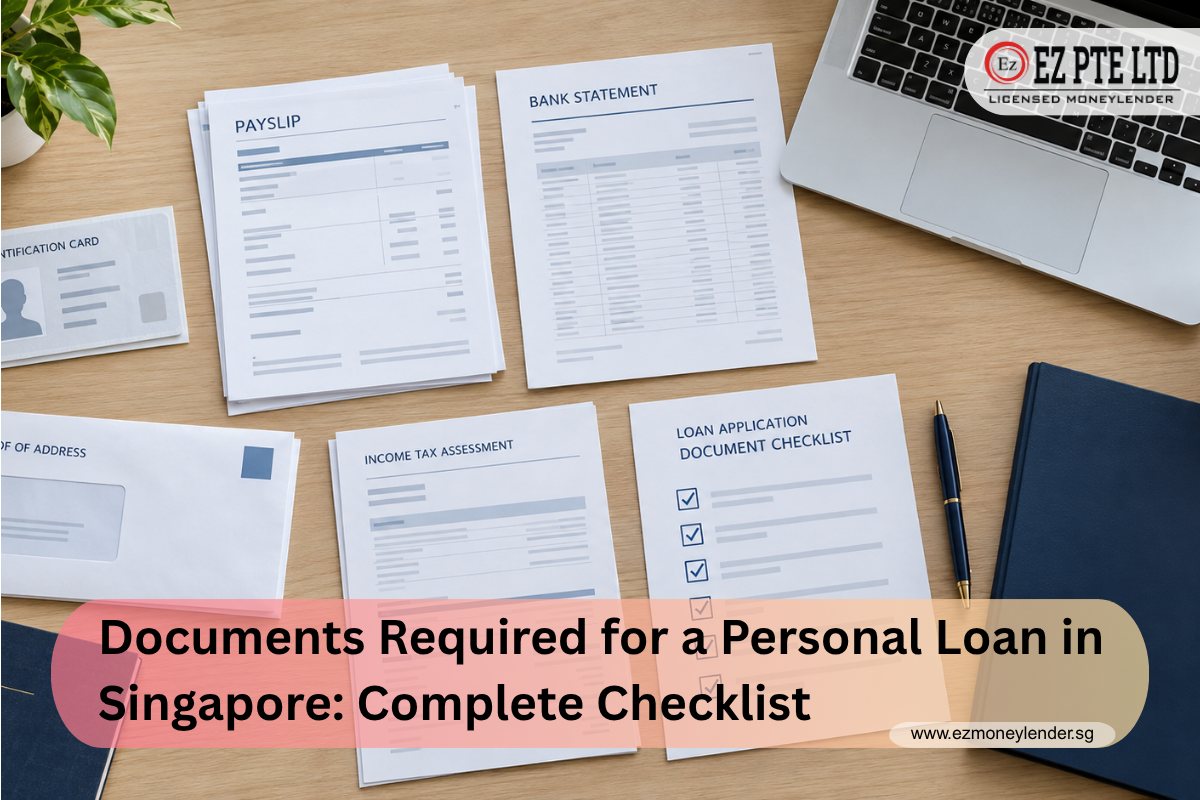
Applicants should prepare current, accurate documents that demonstrate their identity, employment, income and residential address.
| Document | What it helps establish |
|---|---|
| NRIC, passport or valid work pass | Identity and residency status |
| Employment contract | Employer, salary, position and commencement date |
| Appointment letter | Confirmed employment terms |
| Recent payslips | Gross salary, deductions and net pay |
| Bank statements | Actual salary deposits and financial commitments |
| CPF contribution history | Employment and contribution record |
| IRAS Notice of Assessment | Previous declared income |
| Previous payslips | Earlier employment and income continuity |
| Proof of address | Current Singapore residential address |
| Probation confirmation or review letter | Current employment status, where available |
Review EZ Pte Ltd’s loan eligibility requirements before visiting the office.
Employment contract
Your contract or appointment letter should ideally show:
- Employer’s name
- Job title
- Employment start date
- Basic salary
- Allowances
- Probation duration
- Notice period
- Employment type
Provide the complete document rather than only the signature page.
Recent payslips
If you have already received one or more salary payments, bring the corresponding payslips.
A complete payslip may show:
- Basic salary
- Allowances
- Overtime
- Commission
- CPF deductions
- Other deductions
- Net salary
- Pay period
If the first payslip covers only part of a month, explain this clearly. It should not automatically be treated as a normal full-month salary.
Bank statements
Bank statements can confirm that the salary shown in your payslip was credited to your account.
They can also show:
- Existing loan deductions
- Regular household expenses
- Other recurring income
- Returned payments
- Transfers between your own accounts
- Available cash flow after essential expenses
Previous employment records
If you recently moved directly from another job, documents from your former employer may help demonstrate income continuity.
These may include:
- Previous payslips
- Earlier CPF contributions
- Tax records
- Resignation acceptance letter
- Final salary statement
Previous income does not guarantee approval, but it provides more context than the new job alone.
Can You Apply Before Receiving Your First Salary?
You may enquire or submit preliminary information, but approval can be more difficult when no salary from the new employer has been received.
An employment contract shows the agreed salary, while a bank credit and payslip show that employment income has actually started.
If the expense is not urgent, waiting until you receive a full salary payment may provide clearer evidence for the assessment.
Do not borrow solely based on expected income if:
- Your employment start date has not been confirmed
- You have not commenced work
- Your salary amount is uncertain
- Your probation may be extended
- Your earnings depend mainly on unconfirmed overtime or commission
What If Your First Payslip Is Lower Than Your Contracted Salary?
A first salary payment may be lower because you started partway through the month.
For example:
| Item | Amount |
|---|---|
| Contracted monthly basic salary | S$3,000 |
| Employment commenced halfway through the month | |
| First prorated gross salary | S$1,500 |
| CPF and other deductions | −S$300 |
| Illustrative first take-home pay | S$1,200 |
The lender may review the employment contract together with the prorated payslip and salary credit.
However, applicants should avoid assuming that the maximum borrowing amount will be calculated solely using the full contractual salary. The final assessment depends on verified information and the lender’s evaluation.
Does Changing Jobs Affect Eligibility?
Changing jobs does not automatically make someone ineligible.
The assessment may be more straightforward when:
- The new role provides a similar or higher salary
- There was no long employment gap
- The applicant has already received a full salary
- Previous and current employment records are available
- Existing financial commitments remain manageable
- The requested amount is reasonable
The application may require closer review when:
- The applicant changed industries completely
- The new salary depends heavily on commission
- Employment is temporary or project-based
- There was a long period without income
- The employee has not started work
- Documents contain inconsistent information
Declare your current situation accurately. Do not submit old employment information as if it were still current.
What If You Are on Probation and Paid by Commission?
Applicants receiving a basic salary plus commission should separate guaranteed income from variable earnings.
For example:
| Income component | Monthly amount |
|---|---|
| Basic salary | S$2,000 |
| Month 1 commission | S$1,400 |
| Month 2 commission | S$600 |
| Month 3 commission | S$1,000 |
Commission may fluctuate. The strongest month should not automatically be treated as normal monthly income.
Prepare:
- Employment contract
- Commission structure
- Commission statements
- Payslips
- Bank statements
- Records covering several pay periods, where available
Affordability should ideally be tested using basic salary or a conservative income estimate rather than the highest commission month.
How Much Can an Employee on Probation Borrow?
The maximum unsecured borrowing limit depends on annual income and residency status:
| Annual income | Singapore citizens and PRs | Foreigners residing in Singapore |
|---|---|---|
| Below S$10,000 | S$3,000 | S$500 |
| S$10,000 to below S$20,000 | S$3,000 | S$3,000 |
| S$20,000 and above | Up to six times monthly income | Up to six times monthly income |
These limits apply across all licensed moneylenders combined. They do not represent a guaranteed amount from each lender.
An applicant may be offered less after considering:
- Verified salary
- Employment duration
- Existing unsecured loans
- Regular living expenses
- Repayment history
- Requested tenure
- Overall affordability
How Should You Check Affordability?
Use the income you can reasonably depend on—not a future pay increase, bonus or unconfirmed overtime payment.
Consider this simplified monthly budget:
| Monthly budget item | Amount |
|---|---|
| Take-home salary | S$2,700 |
| Rent or household contribution | −S$850 |
| Food and transport | −S$650 |
| Utilities and telephone | −S$150 |
| Insurance and medical expenses | −S$150 |
| Existing repayments | −S$250 |
| Emergency allowance | −S$200 |
| Amount remaining | S$450 |
The remaining S$450 should not automatically become the maximum loan instalment. You still need room for unexpected expenses.
Ask yourself:
- Can I pay the instalment if my probation is extended?
- Can I manage if overtime or commission falls?
- Do I have an emergency reserve?
- Will I still have money for essential expenses?
- Is the amount requested limited to what I genuinely need?
- Could I postpone or reduce the expense?
Use EZ Pte Ltd’s loan calculator to estimate how the amount, tenure and interest rate may affect repayments. Calculator results are illustrations rather than guaranteed offers.
Should You Choose a Short-Term or Monthly Instalment Loan?
The suitable structure depends on the expense, income schedule and repayment capacity.
| Short-term structure | Monthly instalment structure |
|---|---|
| Repaid over a shorter period | Repaid through scheduled monthly instalments |
| May require larger repayments | May produce smaller individual repayments |
| Could suit a temporary cash-flow gap | May suit a larger necessary expense |
| Shorter tenure does not guarantee affordability | Longer tenure may increase total interest |
Applicants can compare an short-term loan with a monthly instalment loan.
Do not choose a loan only because the individual repayment looks smaller. Compare the complete cost and total repayment amount.
What Interest and Fees Can Apply?
Licensed moneylenders may charge interest of up to 4% per month. Interest must be calculated using the outstanding principal remaining after principal repayments have been deducted.
Permitted charges can include:
- An administrative fee of up to 10% of the principal when the loan is granted
- A late fee of up to S$60 for each month of late repayment
- Late interest of up to 4% per month on the overdue amount
- Court-ordered legal costs for a successful recovery claim
The total of regular interest, late interest, administrative fees and late fees cannot exceed an amount equal to the original principal.
Before signing, confirm:
- Principal amount
- Administrative fee
- Net amount received
- Monthly interest rate
- Instalment dates and amounts
- Total scheduled interest
- Total amount repayable
- Late-payment consequences
- Early-settlement procedure
Why Might an Application Be Delayed or Rejected?
No salary has been received
An employment contract states what should be paid but does not prove that income has commenced.
Employment documents are incomplete
A verbal job offer or screenshot may not provide enough information to verify employment.
The first salary is prorated
A partial-month payment may require additional explanation and supporting records.
The requested amount is too high
The statutory borrowing ceiling is not the same as an affordable or guaranteed loan amount.
Existing repayments are substantial
A new salary may still be insufficient after rent, household costs and existing loans are deducted.
Information is inconsistent
Different salary figures, addresses or employment dates can delay verification.
The employment is uncertain
A short temporary contract or unresolved probation review may affect the assessment.
How Can You Prepare a Clearer Application?
Approval cannot be guaranteed, but good preparation makes your circumstances easier to assess.
Wait for a complete payslip when practical
If the expense can wait, one complete pay cycle may provide better evidence than a prorated first salary.
Prepare previous and current records
Show the transition between jobs instead of leaving an unexplained employment gap.
Apply for only what you need
Calculate the actual expense before choosing the amount.
Declare every existing loan
Borrowing limits and affordability assessments consider outstanding commitments.
Use accurate information
Do not inflate income, include unconfirmed bonuses or hide your probation status.
Plan using basic salary
If overtime, allowances or commissions vary, assess affordability using a conservative amount.
How to Apply Safely
Before contacting a lender, verify its company name, approved website and business address using the Registry of Moneylenders’ official list.
Licensed moneylenders cannot solicit loans through unsolicited SMS, WhatsApp messages, phone calls or social-media messages. They must conduct face-to-face identity verification at their approved business premises before granting a loan. A loan transaction conducted entirely online is not permitted.
Avoid anyone who:
- Guarantees approval without assessment
- Requests payment before disbursement
- Asks for a GST or loan-processing transfer
- Requests your Singpass password
- Offers to complete everything remotely
- Arranges to meet outside the registered office
- Asks you to sign a blank contract
- Refuses to explain the repayment terms
Borrowers comparing licensed money lenders in Singapore should verify the lender before providing personal information.
Frequently Asked Questions
Can I get a personal loan while on employment probation?
You may apply. Approval depends on verified income, employment details, current commitments and repayment capacity.
Must I complete three months of employment first?
There is no universal rule requiring every borrower to complete three months. The documents and assessment required depend on the applicant’s circumstances.
Can I apply before receiving my first salary?
You may enquire, but a lender may find it more difficult to verify current income before a salary payment has been received.
Is an employment contract enough?
A contract is useful, but the lender may also request payslips, bank statements, CPF records and other supporting documents.
Can previous employment income be considered?
Previous records may help demonstrate income continuity. However, the lender will still assess your current employment and repayment capacity.
Can a foreign employee apply while on probation?
A foreigner legally residing and working in Singapore may submit an application, subject to a valid pass, document verification, applicable borrowing limits and approval.
Will probation cause a higher interest rate?
The actual offer depends on the applicant’s assessment and loan terms. Licensed moneylenders remain subject to the legal maximum interest rate.
Does completing probation guarantee approval?
No. Confirmation of employment may strengthen income stability, but the lender must still assess expenses, existing loans, repayment history and affordability.
Can I apply completely online?
Preliminary information can be submitted online, but identity verification and completion of the loan must occur face-to-face at the lender’s approved business premises.
How quickly can a probationary employee receive a decision?
Timing depends on the completeness of the documents and complexity of the application. No lender should guarantee approval or disbursement before completing the required checks.
Final Thoughts
You may apply for a personal loan during probation in Singapore, but the strength of the application depends on more than your job title.
Prepare your employment contract, current payslips, salary-crediting bank statements and previous income records. If your first salary is prorated or your earnings include variable commission, explain the figures clearly.
Most importantly, test the proposed repayment using a conservative income amount. A loan should remain manageable even if probation is extended, overtime falls or an expected bonus does not arrive.
Review EZ Pte Ltd’s eligibility criteria and frequently asked questions before deciding whether to apply.
This article provides general educational information and does not constitute financial advice. Every application is subject to assessment, verification and approval.